Two Names on a Car Title
Both names on the title means both of you own the car, but the insurance policy has to name you both separately to actually cover you both.

One Car, Two Names, One Policy With a Gap
Two partners bought a car together and put both names on the title because they'd split the cost evenly. It felt fair and final, so they didn't think much past that. The policy stayed in one partner's name alone, the one who happened to set it up online that week, and neither of them revisited it after the paperwork was signed.
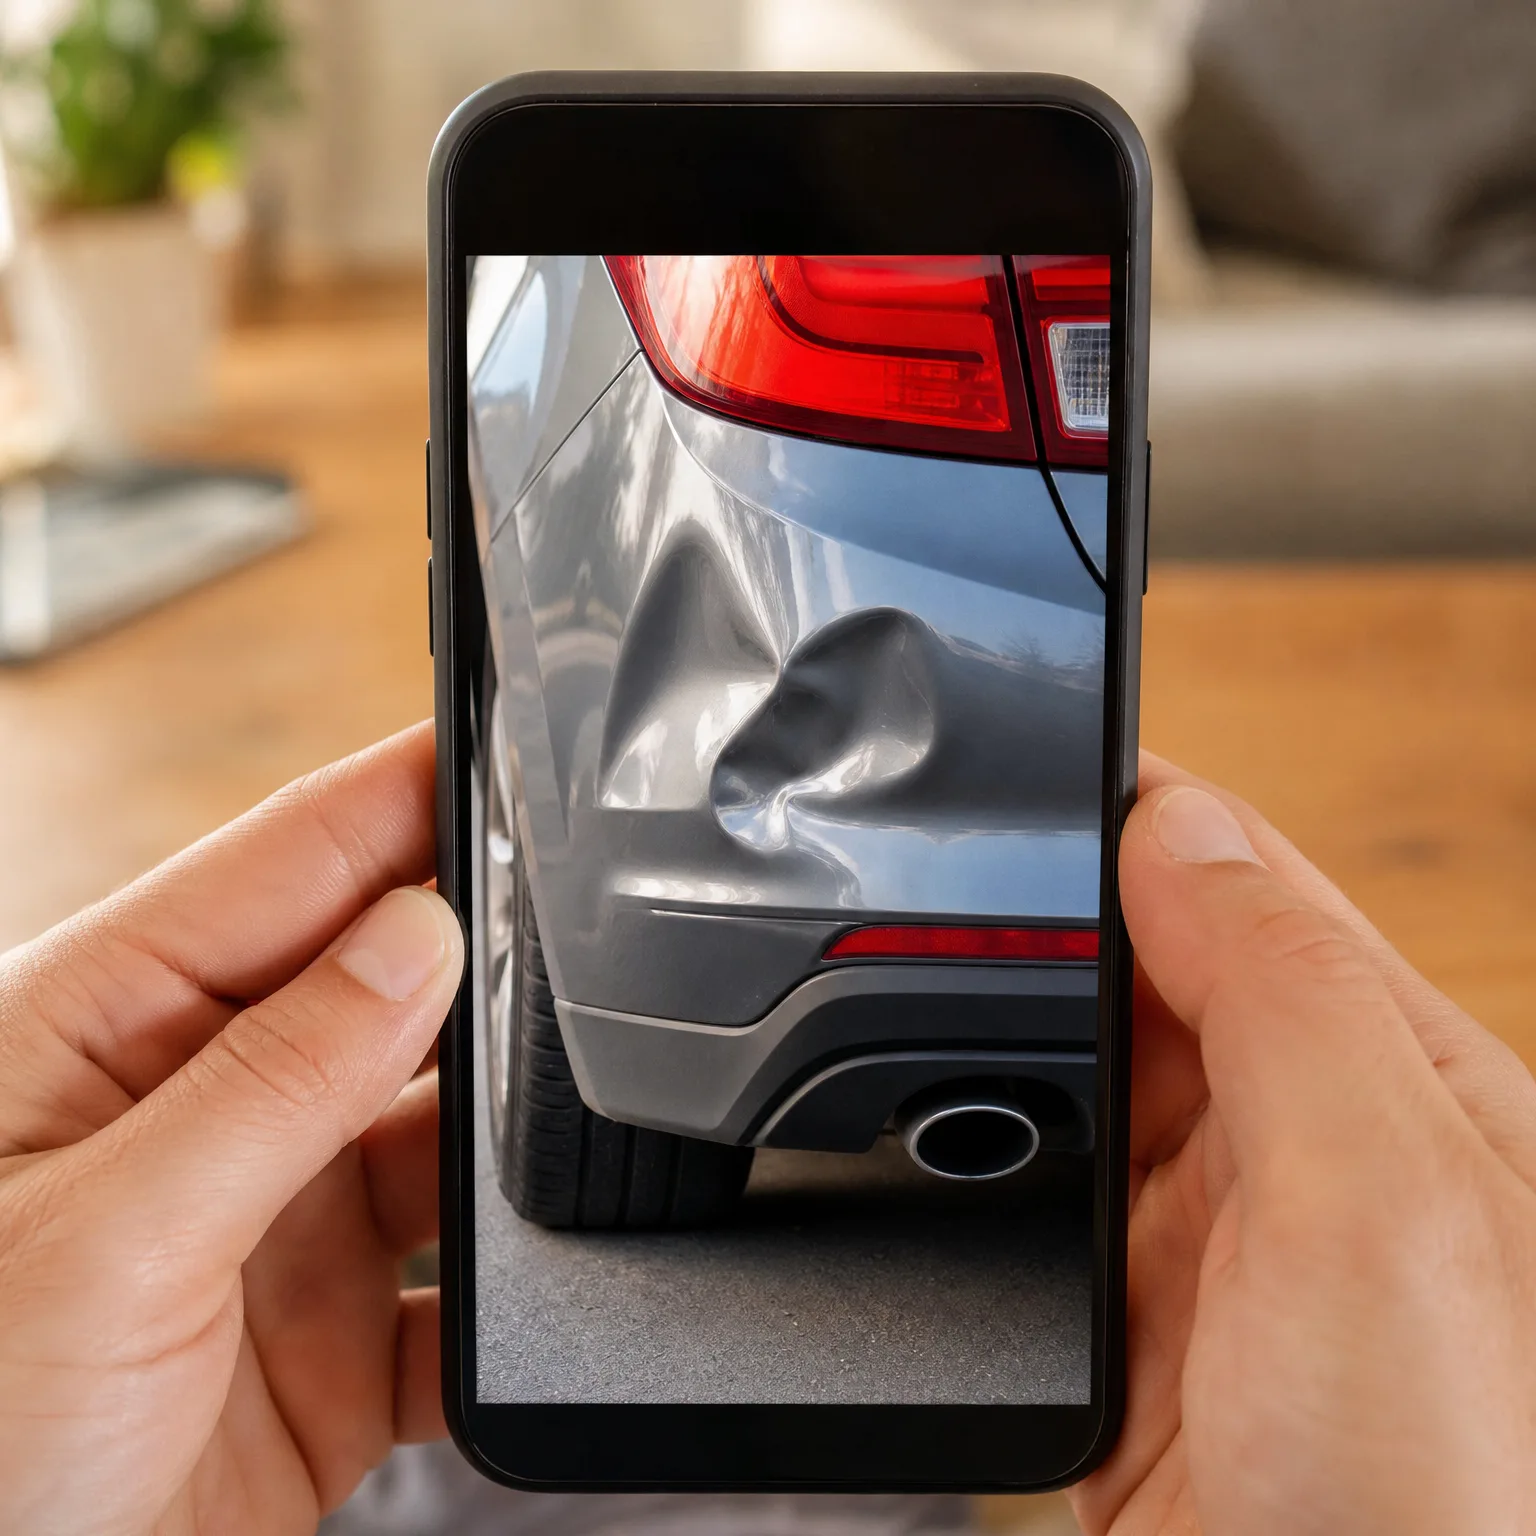
Months later the second partner borrowed the car for a long weekend and was in a minor accident, nobody hurt, just a dented bumper. The claim got complicated because the driver wasn't listed on the policy, even though her name was right there on the title. The insurer eventually covered it but asked pointed questions and flagged the policy for review. After that the couple called their insurer, added both names to the policy to match the title, and it cost less than they expected for the peace of mind.
What happens to the car and the title if we break up?
If both names are on the title, both of you legally own the car and neither can sell it or refinance it without the other's agreement. That's true no matter what the insurance policy says, since the title is the ownership document and the policy is just coverage.
You'll need to agree on who keeps the car and either remove one name from the title through your state's title transfer process, or sell the car and split the proceeds. Until the title is changed, you're both still owners, and whoever's name is on the insurance policy is a separate question you'll also need to settle. Plan for this conversation before it's urgent, not during it.
Now that you know how to match your policy to your title, compare quotes that cover both your names properly.
Matching the Policy to the Title
If you do
Both drivers are clearly covered no matter who's behind the wheel. Claims move faster because the insurer already has both names on file. If you separate, splitting the policy or the car is simpler since the paperwork already reflects shared ownership.
If you don't
The driver left off the policy can still often be covered, but it's the kind of gap that no one has to discover during a routine conversation. It surfaces during a claim, when the insurer asks who was driving and why they weren't listed. That's a hard time to be sorting it out.
The Title and the Policy Answer Different Questions
A title answers who owns the car. A policy answers who's covered to drive it. They don't have to match, but when they don't, you're relying on the policy's rules about permitted drivers to cover someone who's actually a legal owner, and that's a thinner protection than it sounds.
Most insurers will cover an occasional driver who has permission to use the car, even if that person isn't on the policy. But an owner who drives the car regularly, which is common when you live together and share one vehicle, usually needs to be named on the policy as a driver or listed owner. Insurers ask about household members and regular drivers specifically because unlisted regular use is one of the most common reasons claims get delayed or denied.
Unmarried partners don't get automatic treatment the way spouses sometimes do under certain state rules or insurer policies. That's the part that trips people up. You can't assume your insurer treats a live-in partner the same as a spouse just because you share a home and a car title. You have to ask directly and get the answer in writing or in the policy documents.
The cases where it works out differently usually involve one partner who rarely drives the shared car, or two cars each insured separately under each partner's own policy. In those setups, having both names on one title matters less for insurance purposes. What matters is whether the person actually driving is accounted for on the policy covering that car.
Can I remove my name from the car title without my partner's consent?
No, if both names are on the title as joint owners, removing one name requires both signatures in almost every state. This protects both of you from one person unilaterally selling or refinancing the car. If you disagree about who keeps the car, you may need a bill of sale between you or, in rare disputes, legal help to resolve it. Check your state's title transfer process, since the exact form and fee vary.
Does adding my partner to my car insurance raise my rate?
It depends on their driving record, not on the fact that you're unmarried. If their record is clean, adding them often has little effect or even helps by showing the insurer a full picture of household drivers. If they have violations or accidents, expect some increase. Ask your insurer for a quote with them added before deciding, since guessing the impact without checking is unreliable.
Should we combine our policies or keep them separate?
There's no single right answer, it depends on how you share vehicles and how much you trust pooling your rates together. Combining onto one policy with both cars and both drivers often costs less overall and simplifies claims. Keeping policies separate protects each person's rate from the other's driving history and makes splitting up administratively simpler. Compare both setups with real quotes before choosing.